When a market closes: what canola trade disputes teach about market access
Twice in seven years China shut much of its door to Canadian canola. The record of those disputes shows how market access is lost, regained and paid for.
 By Duncan Strathearn9 min read
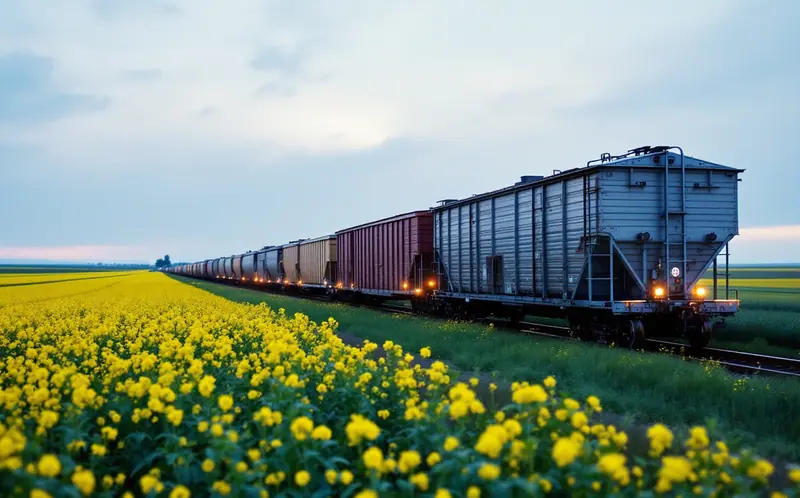
Canola is one of Canada's great export stories, and it has also become the country's clearest lesson in how quickly a foreign market can close. Twice since 2019, China, for years the largest buyer of Canadian canola seed, has restricted imports in ways that had little to do with the quality of the crop and a lot to do with the wider relationship between the two governments. Each time, exporters, crushers and farmers had to adjust, and each time the trade came back on different terms.
This piece walks through those episodes in order, then looks at what they show about market access: how it is lost, how sellers adapt, what the World Trade Organization can and cannot do, and how a price discount at a port finds its way back to a farm in Saskatchewan. It stops at mid-April 2026 and makes no prediction about what comes next.
A crop built for export
Canola was developed in Canada from rapeseed in the 1970s, bred for low levels of erucic acid and glucosinolates so that its oil could be eaten and its meal fed to livestock. It is now grown mainly in Saskatchewan, Alberta and Manitoba, with smaller areas in Ontario and elsewhere.
The Canola Council of Canada says about 90 per cent of the canola grown in Canada ends up in export markets, either as seed or as the oil and meal produced when the seed is crushed. Those products go to different places. The United States is the largest buyer of canola oil and meal. For raw seed, the most important destinations have been China, Japan and Mexico. In 2024 China took about two thirds of Canada's canola seed exports, roughly 5.9 million tonnes, and Canadian seed, oil and meal sold to China were worth about $4.9 billion in total.
That concentration is the background to everything that follows. A seed export business that depends on one buyer for two thirds of its volume has a single point of failure.
The first episode: suspended exporters, 2019 to 2022
What happened
In March 2019 China's customs authority suspended canola seed imports from Richardson International, one of Canada's largest grain companies. Later the same month it cancelled the export registration of Viterra, another major exporter. The official reason given in both cases was the detection of quarantine pests in samples from the companies' cargoes. China also stepped up inspections of seed shipped by other Canadian exporters.
The Canadian Food Inspection Agency did not agree with China's assessment, and both companies said their canola met import standards. The suspensions came a few months after Canadian authorities arrested a senior executive of the Chinese technology company Huawei in December 2018, at the request of the United States. Many observers linked the two, while Beijing maintained that its action was a technical matter. No official document joins them, and this piece does not claim that one caused the other.
What it cost
Seed exports to China fell from about $2.8 billion in 2018 to about $0.8 billion in 2019, then recovered partly to $1.4 billion in 2020 and $1.8 billion in 2021. Trade did not stop entirely, because smaller exporters could still ship, but volumes and prices both suffered.
How it ended
Canada took the case to the WTO. It requested consultations in September 2019, and after a first request was blocked, a dispute panel was established in July 2021 under the case number DS589. The WTO's case page for DS589 records the steps. The panel never ruled. In May 2022 China restored access for the two companies, and in August 2022 Canada asked the panel to suspend its work. The dispute was resolved by a change in policy, not by a judgment.
The second episode: trade remedies, 2024 to 2026
The trigger
The second round started in a different trade fight. In 2024 Canada imposed a 100 per cent surtax on electric vehicles made in China and a 25 per cent surtax on Chinese steel and aluminum. In September 2024 China's Ministry of Commerce opened two investigations in response: an anti-dumping investigation into Canadian canola seed, covering imports in 2023, and a broader "anti-discrimination" investigation into Canadian measures.
The tariffs
From 20 March 2025, as a result of the anti-discrimination investigation, China applied a 100 per cent tariff on Canadian canola oil, canola meal and peas, and 25 per cent on Canadian pork and some seafood.
In August 2025 the anti-dumping case produced a preliminary finding. From 14 August 2025, importers of Canadian canola seed had to post a deposit of 75.8 per cent of the value. On top of the 9 per cent most-favoured-nation tariff China applies to canola seed, that made the Chinese market close to unworkable for Canadian seed. The Government of Canada rejected the finding and said Canada does not dump canola.
The partial reopening
In January 2026 the Prime Minister visited Beijing and the two governments announced a preliminary arrangement. Canada agreed to allow up to 49,000 Chinese-made electric vehicles a year into Canada at a tariff of 6.1 per cent. China said it would bring the combined duties on Canadian canola seed down to about 15 per cent from 1 March 2026.
The details followed at the end of February. China's final anti-dumping determination, issued on 28 February 2026, set a duty of 5.9 per cent for five years. Added to the 9 per cent ordinary tariff, that makes 14.9 per cent. The 100 per cent tariff on canola meal was cut to zero for the period from 1 March to 31 December 2026. Canola oil remained subject to the 100 per cent tariff.
| Date | Measure | Product |
|---|---|---|
| March 2019 | Two major exporters suspended, pest reasons cited | Seed |
| May 2022 | Access restored for both exporters | Seed |
| September 2024 | Anti-dumping and anti-discrimination investigations opened | Seed, then wider |
| 20 March 2025 | 100% tariff | Oil, meal (also peas) |
| 14 August 2025 | Preliminary 75.8% anti-dumping deposit | Seed |
| 28 February 2026 | Final duty of 5.9%, plus 9% ordinary tariff | Seed |
| 1 March 2026 | Meal tariff set to 0% to the end of 2026 | Meal |
How exporters and farmers adjust
When a market closes, the crop does not disappear. It has to go somewhere, and the adjustments come in a fairly predictable order.
- Find other buyers for seed. Exporters push more seed to Japan, Mexico and a longer list of smaller buyers. These markets are real, but most are smaller and some have different quality or sustainability requirements, so moving millions of extra tonnes takes time and usually a lower price.
- Crush more at home. Canadian crushing plants turn seed into oil and meal, most of which go to the United States. More domestic crushing absorbs seed that cannot be exported whole. In the 2019 episode this helped. In 2025 it helped less, because China was also taxing oil and meal, and the US market depends on its own trade policy toward Canada.
- Store and wait. Farmers with bins can hold canola rather than sell at a discount. That shifts the problem into the next crop year and carries costs: interest, storage risk and the chance that prices do not recover.
- Change the rotation. Over a longer period, some farmers plant less canola and more of other crops. That is a slow response, and it brings agronomic and price risks of its own.
A worked example: how a port discount reaches the farm
These numbers are round and purely illustrative. They describe no real price, company or farm.
Say canola delivered to a port terminal is worth $700 a tonne when China is buying normally. Then China raises its duty sharply. Chinese importers either stop buying or will pay only a much lower price before duty. Exporters must find other buyers, and those buyers will take the extra tonnes only at a discount. Say the port price falls by $50, to $650.
The discount does not stop at the port. Grain companies price what they pay farmers backwards from the export or crush value:
| Step | Normal | Market closed |
|---|---|---|
| Value at port | $700 | $650 |
| Rail freight and elevation (assumed) | $70 | $70 |
| Company margin and handling (assumed) | $30 | $35 |
| Price bid to farmer at the local elevator | $600 | $545 |
The farmer's price falls by more than the port price, because freight is fixed and grain companies tend to widen their margin when they are less sure where the grain will go. A farmer who grows 1,000 acres of canola yielding an illustrative 2.5 tonnes an acre has 2,500 tonnes to sell. At $55 a tonne less, that is $137,500 less revenue, from a decision made by a foreign government about a different industry.
Two things soften the hit in practice. Futures prices, which reflect world vegetable oil markets, may not fall as far as local prices if other buyers step in. And some of the loss is passed back to landowners and input suppliers over time. But the first and largest effect lands on the farm gate.
What the WTO can and cannot do
The WTO's dispute system lets one member challenge another's measures before a panel of trade experts. Panels can find that a measure breaks WTO rules on sanitary and phytosanitary measures, anti-dumping procedures or tariff commitments, and the losing member is expected to bring its measures into line.
Three limits matter for a case like canola. First, it is slow. In the first episode, almost two years passed between the request for consultations and the establishment of a panel. Second, the WTO Appellate Body, which hears appeals, has been unable to work since 2019 because its members have not been replaced. A losing party can appeal into a void, and the panel ruling then has no binding effect. Third, a ruling can only address the legal form of a measure. If the underlying cause is political, a government can lift one restriction and impose another.
That is why both canola disputes ended in negotiations rather than rulings. The WTO case was a lever and a record, but the trade came back through bilateral talks. For a parallel case, see how a feed additive became a barrier in the pork trade.
Lessons for market access
The canola record suggests several points that apply well beyond one crop.
Market access is not a single act. It has to be maintained through inspections, technical agreements and diplomatic contact, and it can be withdrawn through any of them. Sanitary and phytosanitary rules, anti-dumping procedures and retaliatory tariffs are different legal tools, but each can close a market.
Concentration is a risk in itself. Selling two thirds of an export product to one buyer is efficient in good years and costly when relations sour. Diversifying is easier to recommend than to do, because the other markets are often smaller and pay less.
Farm products are often caught up in disputes about something else. In 2019 the context was a court case; in 2024 and 2025 it was electric vehicles and steel. Farm exports are visible, politically sensitive in the exporting country and easy to replace for the importer, which makes them a natural target. Canadians who follow supply management will recognise the same pattern of linkage in the bargaining over CUSMA dairy access.
Finally, the costs of a closure fall unevenly. The policy decision is made between governments, but the discount is felt at the local elevator, by the farmers who grew the crop. Anyone following the next round of trade news on canola would do well to watch three numbers: the duty on seed, the status of the meal and oil tariffs after the end of 2026, and the spread between export values and the price bid at prairie elevators. More coverage is collected on the trade and markets page.
Duncan Strathearn
Duncan lives in Kingston, Ontario, and follows agricultural trade talks, tariff schedules and the policy frameworks that sit behind them. He reads trade agreements so readers do not have to.